Silver Rises Over 120% YTD


Factory Costs Hit 82.1. That Number Is Now Working for Your Gold.
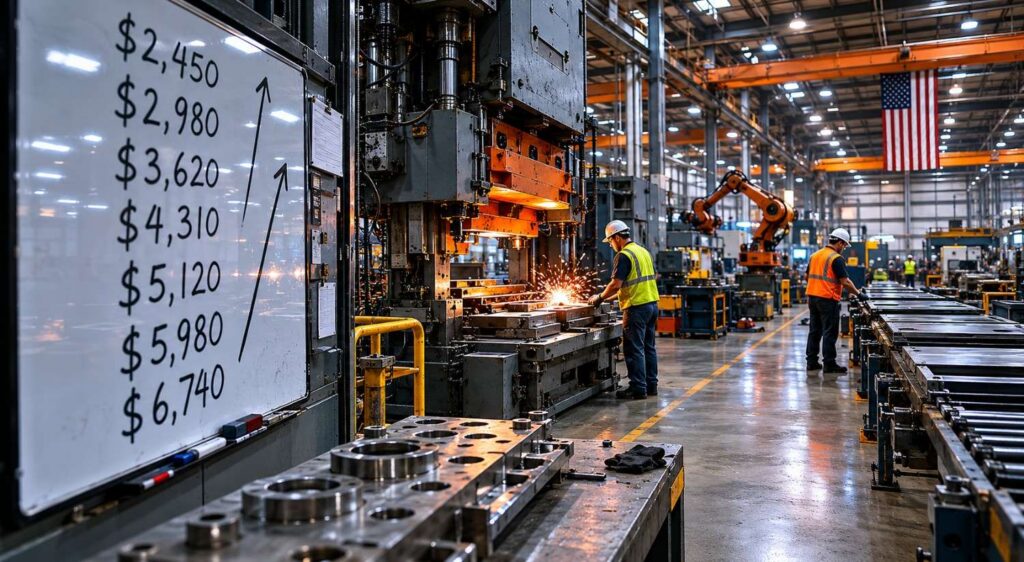
The ISM Manufacturing Prices-Paid Index hit 82.1 in May — the second-highest reading since 2022 and the 20th consecutive month of rising factory costs. Most headlines covered the manufacturing boom. Almost nobody explained what the prices-paid number means for the Fed, for inflation this summer, and for the structural case for holding gold.
Gold at $4,500: What Fort Knox, China, and Silver Are Telling You
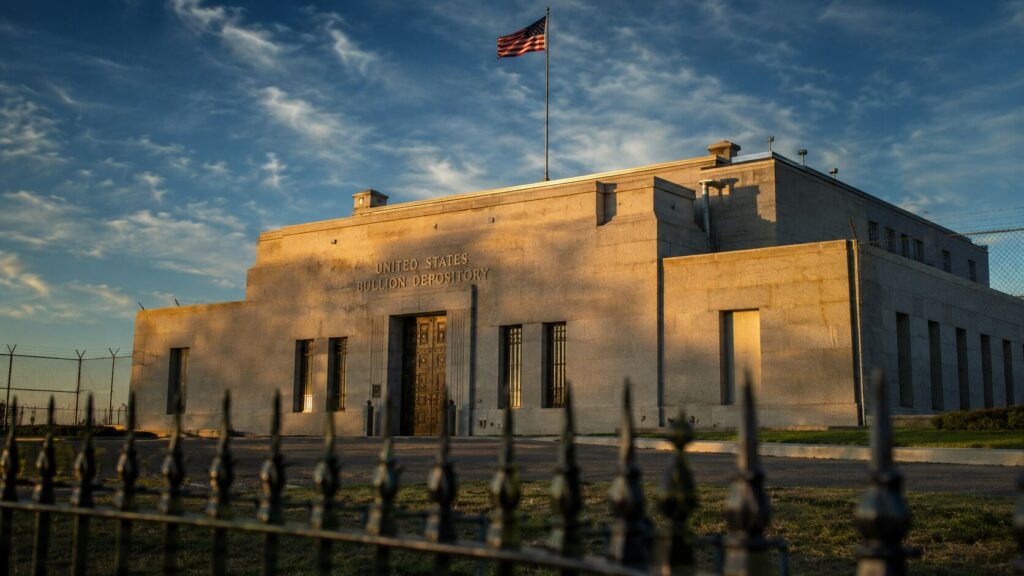
Fort Knox holds $662 billion in gold not independently audited since 1953. China has bought gold for 13 straight months. Manufacturers are signaling inflation isn’t finished. Fourteen states just made gold and silver constitutional money. And silver is outperforming gold 2:1 today. Five stories. One through-line. Here’s what they mean for your metals.
The Gold-Silver Ratio Is Expanding — and Being Misread
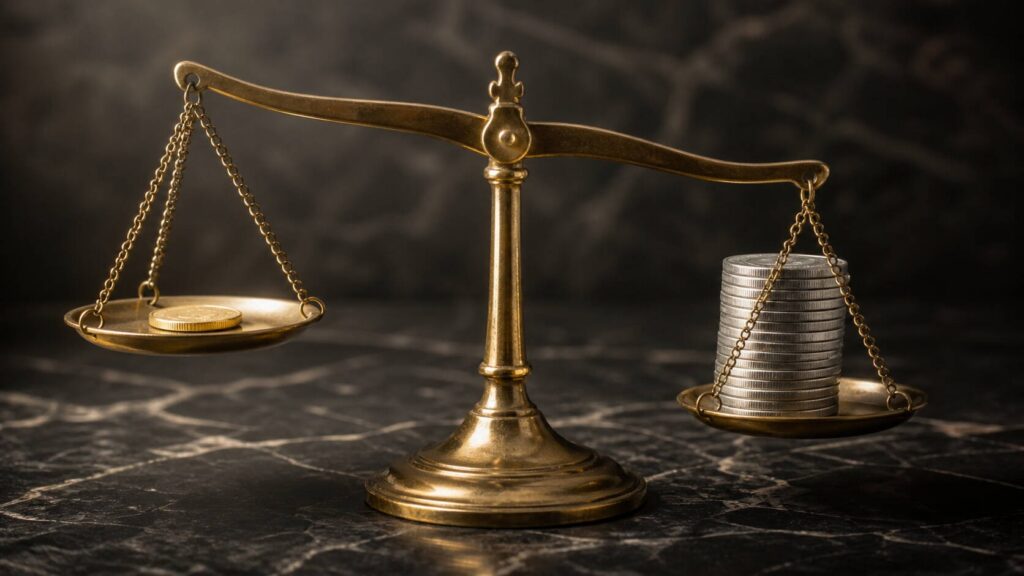
The gold-silver ratio has expanded to 62.05:1 — silver is down ~7% since April 22 versus gold’s ~4%. Most investors are reading that as a bearish signal. Here’s why the ratio expansion is a short-term positioning story, and why the structural case for silver — six consecutive supply deficits, record China demand, Basel III tailwinds — has not changed.
Why Gold Fell on the Hormuz Tanker Strike
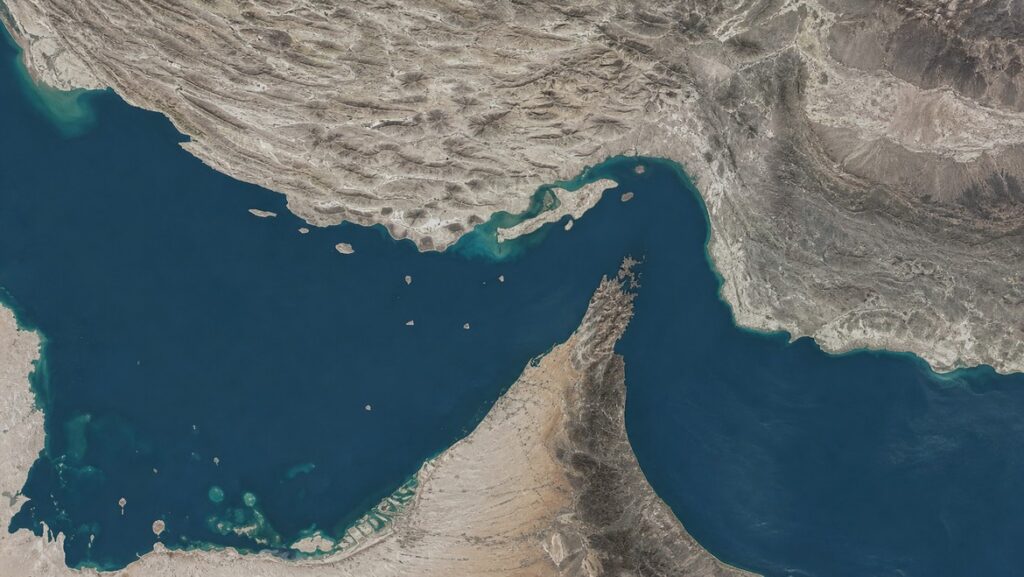
The gold price dropped on May 4, 2026, as a tanker was struck in the Strait of Hormuz and ISM Prices Paid hit 84.6 — the worst cost-inflation reading since April 2022. Gold barely moved. Here’s what that non-reaction tells investors about where the structural floor really is.
The Stagflation 2026 Warning Hidden in Today’s Data
Stagflation 2026 risks intensified Wednesday as oil surged past $111, manufacturing prices hit their highest level since June 2022, and U.S. hiring fell to its weakest point since the COVID shutdowns. The Fed has no clean way out.