Silver Rises Over 120% YTD


Manufacturing Hit a Four-Year High Today. Gold Didn’t Move. Here’s Why That’s the Story.
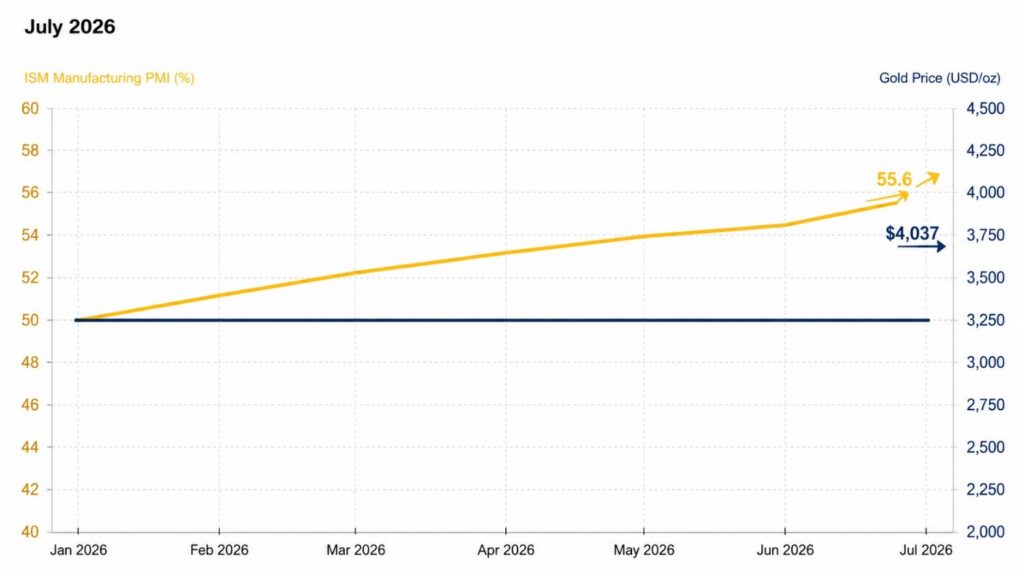
The ISM Manufacturing PMI just hit 55.6% — its strongest reading since May 2022. Gold barely moved. That non-reaction isn’t a failure to respond. It’s gold caught between two opposing forces that are almost perfectly canceling each other out, and this week’s data decides which one breaks first.
Hike Odds Doubled. Gold Is Down $46. Here Is Why.

Gold is down $46 this morning as Fed rate hike odds have quietly doubled from 16% to 36.5% in two weeks. Here is the four-step real yield mechanism behind today’s move — and why the structural case for gold remains intact.
Gold Holds $4,481 With Rate Hike Risk Rising. Here’s the NFP Decision Map.
Gold is holding near $4,481 with rate hike risk rising — a divergence that, in any prior rate cycle, would have already sent gold lower. Tomorrow’s May jobs report is the last major data point before Warsh’s first FOMC meeting June 16–17. Here’s the three-scenario decision map: what a hot print, an in-line print, and a soft miss each mean for gold — and why the Fed’s policy trap makes the structural case for sound money regardless of Friday’s number.
Factory Costs Hit 82.1. That Number Is Now Working for Your Gold.
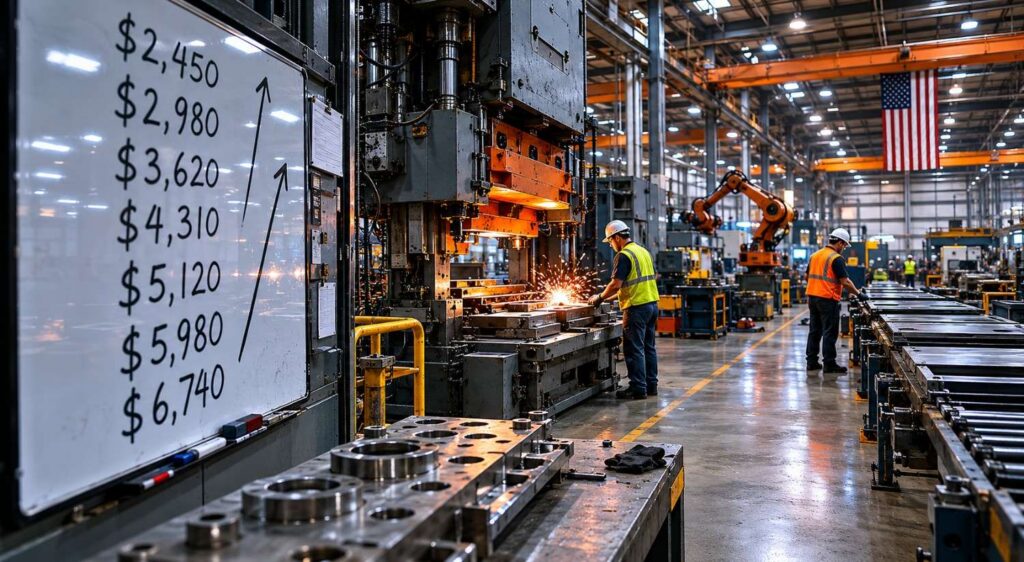
The ISM Manufacturing Prices-Paid Index hit 82.1 in May — the second-highest reading since 2022 and the 20th consecutive month of rising factory costs. Most headlines covered the manufacturing boom. Almost nobody explained what the prices-paid number means for the Fed, for inflation this summer, and for the structural case for holding gold.
The Stagflation 2026 Warning Hidden in Today’s Data
Stagflation 2026 risks intensified Wednesday as oil surged past $111, manufacturing prices hit their highest level since June 2022, and U.S. hiring fell to its weakest point since the COVID shutdowns. The Fed has no clean way out.