Silver Rises Over 120% YTD


Published: 09-14-2026, 02:35 pm
Key Takeaways
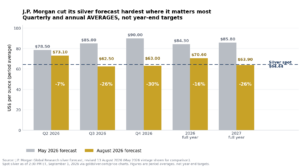
- Silver trades near $63.72 an ounce, about 47.6% below its January 29, 2026 record of $121.62 [CME Group]
- The Fed’s September 15-16 meeting concludes September 16; CME FedWatch prices a quarter-point hike at roughly 85-91% depending on the reading, up from 66% two weeks earlier [CME Group]
- Speculative silver longs have rebuilt to 25.2% of open interest, the 73rd percentile of the past 60 weeks, up from the 20th percentile in mid-August [CFTC]
- The 10-year real yield (TIPS) has risen to 2.55%, roughly 20 basis points higher than mid-August, the mechanism behind silver’s continued underperformance versus gold [Treasury]
- Silver’s sixth consecutive annual deficit is forecast at 46.3 million ounces, wider than 2025’s 40.3 million, bringing the cumulative shortfall since 2021 to 762.1 million ounces [Silver Institute]
- August CPI held at 3.4% annually while core cooled to 2.4%, the lowest since March 2021, but a Middle East-driven oil spike pushed rate-hike odds higher anyway [BLS]
Silver trades near $63.72 an ounce heading into the Fed’s September 15-16 meeting. That’s about 47.6% below its January 29 record of $121.62. A quarter-point hike is now priced at roughly 85-91% depending on the reading, nearly a certainty either way. What isn’t settled is the position underneath that price. Speculative silver longs have quietly rebuilt to the 73rd percentile of the past 60 weeks, into a market that keeps falling. That rebuild, not the hike itself, is the part of this setup worth understanding before Wednesday’s decision.
Why Does a ~90% Probable Fed Hike Still Matter for Silver?
Because a probability isn’t a certainty, and the number that actually moves silver is real yields, not the vote count. CME Group’s FedWatch tool puts hike odds in the 85-91% range for September 16, depending on the intraday reading, up from about 66% on August 31 [CME Group]. Two forces drove that repricing. August’s inflation data was one. A Middle East oil shock was the other. Headline CPI held at 3.4% annually while core cooled to 2.4%, the lowest reading since March 2021 [BLS]. Producer prices ran hotter, up 5.4% year over year [BLS]. Then a Saudi pipeline attack pushed crude above $100 a barrel. That added a fresh inflation impulse with nothing to do with domestic demand. It is a supply shock the Fed cannot lower rates to fix.
The 10-year Treasury yield has climbed to roughly 4.97%, its highest since October 2023 [Treasury]. The 10-year TIPS yield, the market’s direct real-yield reading, sits at 2.55% as of the most recent published figure, up from about 2.35% in mid-August [Treasury]. This roughly 20-basis-point move is the actual mechanism at work. Real yields set the opportunity cost of holding a metal that pays no yield. Silver carries less monetary demand than gold, so it absorbs more of that pressure at the margin.
There is a second layer most coverage skips. This is Chair Kevin Warsh’s first rate hike since taking over the Fed in May. He has not submitted a personal projection to the Summary of Economic Projections dot plot at any meeting since. He’s the first chair to withhold one since the dot plot began in 2012 [Federal Reserve]. The decision itself may be close to fully priced. The other 18 participants’ dots, and how many now project a second hike, are not. Fed funds futures already price the policy rate reaching roughly 4.1% by December and about 4.6% by September 2027 [CME Group]. If Wednesday’s dot plot confirms that path, the mechanism above keeps running. If it doesn’t, the market has to unwind a lot of that repricing fast.
The Knowledge That Changes Everything
Two essential guides — yours free. Understand why gold matters and why fiat currencies always fail.
Why Are Speculative Silver Longs Rebuilding Into a Falling Market?
Because net length as a share of open interest is the crowding measure that matters, not the raw contract count. That share has been climbing while price falls. CFTC data show speculative net long positioning in COMEX silver futures at 25.2% of open interest as of September 8. That’s the 73rd percentile of the past 60 weekly readings [CFTC]. It’s up from 19.7% on August 18, when this series last called silver’s positioning washed out [CFTC]. The rebuild happened almost entirely on the long side. Gross short positions have stayed comparatively thin through the period. That matters, because thin shorts remove the short-covering cushion: the natural bid that forms when a falling market forces short sellers to buy back their positions. Without that cushion doing much work, the longs added since mid-August are the exposed position now.
That is a genuinely different setup than the one this series described in August. A market that has already flushed its speculative longs has limited room left to fall on forced selling. A market that has quietly rebuilt its longs into six weeks of declining price has more room to move, in either direction. A dot plot confirming the hawkish path gives those longs a reason to capitulate. A dot plot that comes in softer than today’s odds assume gives them a reason to add instead, since the position is already built.
How Wide Is the Physical Silver Deficit, and Does It Care About the Fed?
Not directly, and that is the point. The Silver Institute’s World Silver Survey 2026 confirms silver’s fifth consecutive annual deficit ran through 2025 at 40.3 million ounces. It forecasts a sixth consecutive deficit in 2026, at 46.3 million ounces, a wider shortfall than the year before [Silver Institute]. Cumulative drawdown of above-ground stocks since 2021 now totals 762.1 million ounces [Silver Institute]. None of that moves because the Federal Open Market Committee votes on Wednesday. Mine supply is rigid. Most silver comes as a byproduct of gold, copper and zinc mining, so a higher price doesn’t quickly produce more metal. Industrial demand from electronics and solar responds just as slowly to a 25-basis-point move.
What this week’s decision sets is the paper price: the number trading on futures exchanges, reacting to real yields within minutes. The deficit sets a different price, the physical one. That shows up in premiums, delivery queues, and how much metal is actually available when large buyers want it. Those two prices can diverge for a while, as they have through 2026. They do not diverge forever. The paper market eventually has to clear against physical availability. A rate decision changes this week’s number. It does not touch the six-year trend underneath it.
What Would Actually Move Silver After September 16?
Four things, in order of how soon they land. First, the dot plot itself. Watch how many of the 18 remaining participants project a second hike by year-end, since that dispersion is what futures markets already price toward 4.1% by December [CME Group]. Second, Chair Warsh’s press-conference language. He has shortened post-meeting communication since May and declined to offer his own forward guidance [Federal Reserve]. Third, whether the 10-year real yield extends past 2.6% or reverses. That single number has explained most of the gap between gold’s 22.9% pullback from its own January record and silver’s steeper 47.6% decline [Treasury]. Fourth, the World Gold Council’s third-quarter central bank buying data. The quarter itself closes September 30, but the Gold Demand Trends report typically follows about five weeks later, based on the Q2 report’s own lag; when it lands, it sets the tone for cross-metal demand heading into year end.
The gold-silver ratio has told a fairly stable story through the back half of the year. It touched 70:1 on July 15, when gold traded near $4,056 and silver near $57.84. It sits close to 68:1 now, with both metals near their September levels. Two months of range-bound behavior in the high-60s to low-70s reads less like a clean trend. It looks more like a market waiting for the next real-yield move to actually resolve it, which is exactly what Wednesday is positioned to provide.
Read more in August’s edition of this series, whose positioning read this piece updates, and in this month’s Gold Price Outlook, which covers the same FOMC meeting from gold’s side of the trade.
Stay On Top of Gold & Silver Prices
Get important market alerts sent straight to your inbox.
People Also Ask
The physical market is running its sixth consecutive annual deficit, forecast at 46.3 million ounces in 2026, while the paper price has fallen 47.6% from January’s record [Silver Institute]. Those two facts point in different directions. Whether $63 undervalues silver depends on which mechanism resolves first: the real-yield pressure setting this week’s price, or the structural deficit that has drawn down 762.1 million ounces of above-ground stock since 2021.
That depends on what happens to real yields after the decision, not the decision itself. If the 10-year real yield, near 2.55% now, keeps climbing after Wednesday, the mechanism pressuring silver keeps running. If the dot plot signals fewer additional hikes than today’s pre-positioned odds assume, real yields have room to ease. That is the more likely trigger for a recovery than the hike print itself.
Silver carries less monetary demand and more industrial exposure than gold. It takes a larger share of any real-yield move as a result. The ratio has held in a 67-to-70 range since mid-July. That’s consistent with a market where the real-yield mechanism, not a change in either metal’s fundamentals, is doing most of the work.
The September SEP dot plot, released alongside Wednesday’s decision. Then the World Gold Council’s third-quarter central bank data, covering the quarter that closes September 30 but not published until roughly five weeks later. Then the next Consumer Price Index report, scheduled for October 14 [BLS].
SOURCES
1. CME Group, FedWatch Tool — hike-probability tracking
2. U.S. Bureau of Labor Statistics — Consumer Price Index, August 2026 (bls.gov)
3. U.S. Bureau of Labor Statistics — Producer Price Index, August 2026 (bls.gov)
4. U.S. Department of the Treasury — daily Treasury yield curve rates
5. Board of Governors of the Federal Reserve System — Summary of Economic Projections
6. Commodity Futures Trading Commission — Commitments of Traders, COMEX Silver (Legacy, Futures Only)
7. The Silver Institute — World Silver Survey 2026 (Metals Focus)
8. World Gold Council — Q2 2026 official-sector gold purchases
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Always consult a qualified financial advisor before making investment decisions.
You May Also Like:
- Gold Is About to Face Its First Rate Hike of the Cycle. Here’s Why It Isn’t Scared.
- How Much Gold Should You Own at 25, 45, or 65?
- Gold Price Outlook September 2026: What the Fed’s September 15-16 Meeting Means for Your Metals
- Do You Have to Report Gold Stored in a Foreign Vault? FBAR and FATCA Rules Explained
- Tokenized Gold: What It Actually Is, and Where the “Just Like Owning Gold” Pitch Breaks Down
- IRA-Eligible Gold: The Coins and Bars That Actually Qualify
- The No-Home-Storage-IRA Myth: Why the IRS Requires a Depository
- What Is a Gold IRA? The Purity Rule the IRS Never Wrote