Silver Rises Over 120% YTD


Published: 09-18-2026, 11:34 am
Last verified: September 2026
A silver allocation is the share of a portfolio held in physical silver. The right way to size it, however, is not a standalone percentage. Instead, it is a fraction of whatever an investor already allocates to gold, translated using the gold-silver ratio.
Most guidance sizes silver at 10 to 30 percent of the dollar value already allocated to gold. Notably, it is not a separate share of the total portfolio. A 25-year-old with a 10 percent gold position might add silver worth 20 to 30 percent of it. In contrast, a 65-year-old typically holds closer to 10 to 15 percent.
As of September 2026, the gold-silver ratio sits near 65.6. Specifically, that means it takes about 65.6 ounces of silver to buy one ounce of gold. The ratio is down sharply from the low 90s in early 2025, as silver has outrun gold on tightening physical supply and steady industrial demand. Ray Dalio has repeatedly argued that a diversified portfolio should hold 5 to 15 percent in gold. GoldSilver’s own age-based framework already builds on that range. Meanwhile, silver carries roughly 61 percent industrial demand exposure, up from 53 percent a decade ago per the World Gold Council. That sits on top of the same monetary drivers that move gold. As a result, that extra exposure is why silver swings harder in both directions. That is also why the sound approach sizes silver as a fraction of the gold position. It beats picking an independent number out of thin air.
Key takeaways:
- Silver has no standalone institutional allocation rule the way gold has Dalio’s widely cited 5 to 15 percent. Instead, size silver as a fraction of an existing gold position, not as its own fixed share of the total portfolio.
- The gold-silver ratio, near 65.6 as of September 2026, is the actual tool for making that translation. It has, in fact, compressed from the low 90s in early 2025 as silver has outperformed.
- Younger, growth-oriented investors can reasonably run silver at 20 to 30 percent of their gold allocation’s dollar value. Investors closer to retirement, however, typically run it lower, near 10 to 15 percent, because silver’s volatility cuts against near-term capital needs.
- CFTC positioning data shows speculative silver longs building through the summer of 2026, but not at a historical extreme. As a result, that undercuts the “it’s too late” objection with actual numbers instead of sentiment.
- Roughly 72 percent of family offices report zero gold exposure at all, according to In Gold We Trust 2026’s synthesis of J.P. Morgan’s 2026 Global Family Office Report. So for most investors, the real starting question is not “how much silver.” It is, instead, “do I have any precious metals exposure at all.”
Search “how much silver should I own” and the honest answer, in fact, is that almost nobody has a real one. Stacking accounts on TikTok and X circulate gold-to-silver splits like 70/30, 90/10, and 50/50 with total confidence and zero backing. GoldSilver already published the age-based framework for gold. This piece, therefore, extends it to silver, using the ratio and silver’s own risk profile instead of a guess passed around in a comment section.
How Much Silver Should You Own at 25, 45, or 65?
The starting point is always the gold position, sized per the age-based framework GoldSilver has already laid out. From there, add silver as a fraction of that gold allocation.
Building wealth (20s-30s). A gold position of roughly 5 to 10 percent of the portfolio works here. Specifically, add silver at 20 to 30 percent of that gold allocation’s dollar value. A longer time horizon absorbs silver’s sharper swings, and its industrial-demand upside is, in fact, a genuine reason to lean in rather than avoid it.
Peak earning years (40s-50s). A gold position of roughly 8 to 12 percent fits this stage. Similarly, add silver at 15 to 20 percent of that allocation. This is the balanced middle of the framework: meaningful silver exposure, without letting a volatile satellite position dominate the metals sleeve.
Approaching or in retirement (60s+). A gold position of roughly 10 to 15 percent is typical here. Instead, dial silver back to 10 to 15 percent of that allocation. Capital preservation matters more at this stage, and, as a result, silver’s volatility works against near-term liquidity needs.
None of these are fixed rules handed down by an institution. Instead, they scale Dalio’s gold guidance using the one fact that actually differs between the two metals. Silver simply moves harder, in both directions, than gold does.
The Knowledge That Changes Everything
Two essential guides — yours free. Understand why gold matters and why fiat currencies always fail.
What Is the Gold-to-Silver Ratio, and Why Does It Matter for Sizing?
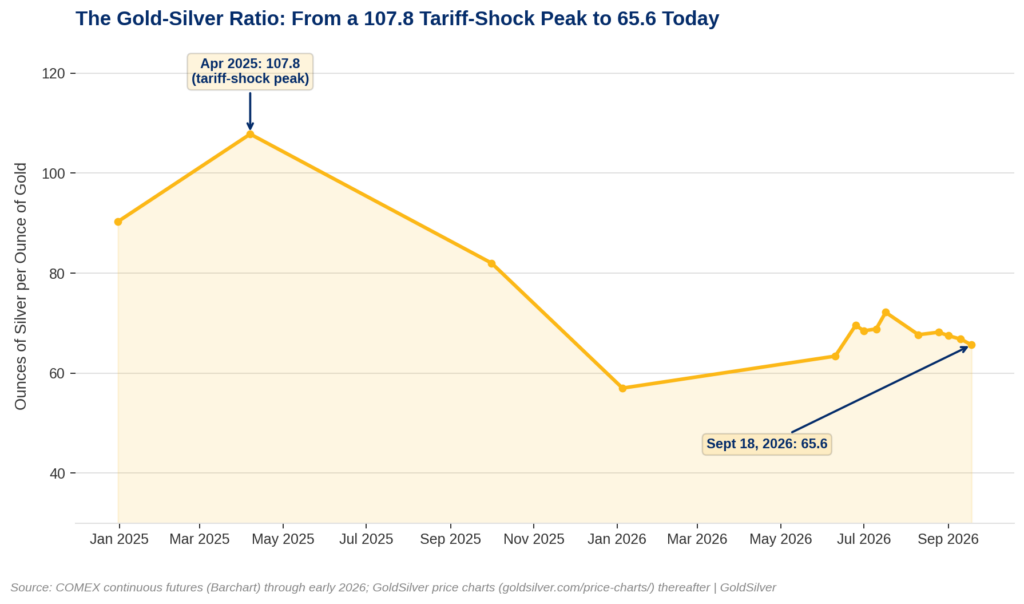
The gold-silver ratio measures how many ounces of silver it takes to purchase one ounce of gold at current prices. As of September 18, 2026, gold trades near $4,367.61 and silver near $66.54 per ounce. That puts the ratio at roughly 65.6. The figure, however, is not a forecasting tool. It is, instead, a translation tool. Specifically, it tells an investor how the two metals are priced relative to each other right now. Notably, that is the missing input every ungrounded social-media split leaves out.
A ratio in the mid-60s sits below its multi-decade historical average, which has run closer to 60-to-70 over long stretches. It also sits well above the tightest historical readings, near 15-to-20, that have accompanied genuine silver squeezes. In other words, silver is neither at a screaming discount nor at a speculative extreme relative to gold today. That is useful precisely because it removes the guesswork the 70/30-versus-90/10 debate is missing.
Why Does Silver Swing Harder Than Gold?
Silver has a dual identity that gold does not share. Both metals, for example, respond to the same monetary drivers. Real yields sit near 2.68 percent on the 10-year Treasury, and breakeven inflation expectations sit near 2.33 percent, both as of mid-September 2026. Silver, however, also carries roughly 61 percent industrial demand, feeding solar panels, electronics, and increasingly data centers, on top of that monetary demand. As a result, a slowdown in industrial orders, or a burst of speculative interest, can move silver independently of anything happening to gold.
That dual exposure is the actual mechanism behind silver’s higher volatility. It is not, in other words, a vague claim that “silver is riskier.” It is also, therefore, the reason silver’s allocation should come from the gold allocation, rather than get set on its own. Gold is the stable core exposure to monetary debasement. Silver, in contrast, is the higher-beta satellite that adds industrial-cycle upside at the cost of sharper drawdowns.
Is It Too Late to Add Silver Right Now?
CFTC Commitments of Traders data tells a calmer story. Managed-money net-long positioning in COMEX silver built from roughly 22,200 contracts in late July 2026 to roughly 26,700 by early September. Indeed, that is a real increase in speculative interest. Still, it remains well short of the crowded extremes that have historically preceded sharp reversals. In short, positioning is building, not blown out.
The gold-silver ratio tells a similar story: compressed, but not at a historical floor. Together, the data supports a narrower claim than the headline question implies. The easiest part of the recent silver move has, in fact, likely passed. Current positioning, however, does not look like a market that has already run out of buyers. That is a meaningfully different statement than “silver will keep going up,” and it is the honest one the data actually supports.
What Does Warren Buffett Actually Say About Silver?
Buffett has been openly skeptical of precious metals for decades. His argument is straightforward: gold and silver produce nothing, and generate no cash flow the way a productive business does. That skepticism, notably, deserves a direct answer, because it is the strongest version of the counterargument to any allocation at all.
Buffett’s critique, in fact, is correct on its own terms. Indeed, silver will never pay a dividend or compound earnings. It also, however, is not trying to. A silver allocation, like a gold allocation, functions instead as insurance against monetary debasement and as portfolio-level diversification. It is not a growth engine competing with equities. Consequently, an investor who wants Buffett-style compounding should get that from equities, and size silver as the smaller, purpose-built piece of the portfolio described above.
Where Do Gold, Silver, and Real Yields Stand Today?
As of September 18, 2026, gold trades near $4,367.61 an ounce and silver near $66.54. Both are little changed on the day, and both are up meaningfully from where they opened 2026. The 10-year real yield sits at 2.68 percent, while the 10-year breakeven inflation rate sits at 2.33 percent. Together, they are a mild opportunity-cost headwind for both metals, not a restrictive one. None of that, however, changes the sizing framework above. It is, instead, the backdrop the framework has to work in, not a reason to abandon it.
Why Does Just Picking a Percentage Miss the Real Problem?
The surface take on this question is simple: pick a number, like 10 percent, and move on. Most of the guessing on social media stops there.
That take is incomplete, however. It treats silver as if it were a smaller version of gold, when it is actually a different asset wearing gold’s monetary reputation. Specifically, a fixed percentage ignores the ratio, which shows how the two metals are priced relative to each other right now. It also ignores silver’s industrial-demand exposure, the actual source of its extra volatility.
The deeper dynamic, in fact, runs further back than sizing at all. Most investors are not choosing between a 10 percent silver allocation and a 15 percent one. According to In Gold We Trust 2026’s synthesis of J.P. Morgan’s 2026 Global Family Office Report, 72 percent of family offices hold no gold exposure whatsoever. Similarly, UBS data cited in the same research puts US retail gold ETF exposure at just 0.17 percent of portfolios. The real decision most readers face, therefore, is not “how much silver.” It is “do I have any precious metals exposure at all.” Silver sizing only becomes the live question once that first one is answered.
What that sets up next, then, is a practical, and separate, question. Once someone picks a target allocation using the framework above, how do they actually build to it? Staged buying over several months, rather than a single lump purchase, is the common answer among experienced holders. As a result, it removes the pressure to correctly time an entry into a volatile asset. Sizing and timing, in short, are two different decisions. This article answers the first one honestly, rather than pretending to answer both.
What Does This Framework Mean for Gold and Silver Investors?
The practical version of this framework, in short, is simple. First, decide a gold allocation using age and goals. Then, size silver as a fraction of that gold position, rather than as an independent guess. Next, use the current gold-silver ratio as the translation tool. Lean toward the higher end of the silver range if the time horizon is long and the industrial-demand story genuinely interests you. Otherwise, lean toward the lower end if capital preservation matters more than upside. None of this, notably, requires predicting where either metal goes next. It only requires being honest about what each metal actually is.
Stay On Top of Gold & Silver Prices
Get important market alerts sent straight to your inbox.
People Also Asked
What is a good gold-to-silver ratio for a portfolio?
There is no single “good” ratio. Instead, it measures market pricing, not allocation. As of September 2026, the ratio sits near 65.6. That means it takes about 65.6 ounces of silver to buy one ounce of gold. Investors use it to translate a gold allocation into a silver one. Specifically, that typically means sizing silver at 10 to 30 percent of the dollar value already in gold.
Should I own silver instead of gold, or both?
Most frameworks treat silver as a smaller addition to gold, not a replacement. Gold responds mainly to monetary drivers like real yields. Silver, however, carries those same drivers plus roughly 61 percent industrial demand. That combination makes silver more volatile. As a result, it typically works best as a satellite position, sized as a fraction of an existing gold allocation.
How do I actually build a silver position in the right proportion?
Most experienced holders build a silver position in stages. Specifically, they buy over several months rather than making one lump purchase, to avoid the pressure of timing a volatile asset. A practical approach picks a target allocation first, using the age-based framework above. Then, it commits to that target through smaller, regularly spaced purchases. Sizing and timing, in other words, are separate decisions.
What are the risks of owning too much silver relative to gold?
Silver’s roughly 61 percent industrial demand exposure means its price can swing on manufacturing cycles. Notably, those cycles have nothing to do with monetary policy. Over-weighting silver relative to gold, therefore, adds volatility without a proportional increase in the monetary-debasement protection gold provides. That is why age-based frameworks cap silver at a fraction, not a majority, of a combined metals allocation.
How does this compare to GoldSilver’s age-based gold allocation guide?
This framework starts from that same gold guide and extends it, rather than replacing it. The gold percentages by decade stay unchanged. Silver, instead, is added as a fraction of whichever gold allocation an investor’s age and goals already point to. The current gold-silver ratio is the translation tool.
What happens to silver if the economy weakens or industrial demand slows?
A slowdown in industrial demand would likely widen the gold-silver ratio. Specifically, silver would lose one of its two demand drivers while gold’s monetary demand held up. That scenario, in fact, is the practical argument for sizing silver as a fraction of gold, not an equal position. Gold simply carries less industrial-cycle exposure.
What does Warren Buffett say about silver?
Buffett has been openly skeptical of precious metals for decades. His argument, notably, is that they generate no cash flow the way a business does. That critique is accurate on its own terms: silver pays no dividend and compounds no earnings. It functions instead as insurance against monetary debasement, a different job than the growth role equities play.
How much silver does the average person own?
There is no precise public figure for silver specifically. However, the closest data points to broad underexposure to precious metals generally. In Gold We Trust 2026’s synthesis of J.P. Morgan’s 2026 Global Family Office Report, for example, found 72 percent of family offices hold no gold exposure at all. Similarly, UBS data cited in the same research puts US retail gold ETF exposure at just 0.17 percent of portfolios. Silver ownership, as a result, is reasonably assumed to be thinner still.
SOURCES
1. GoldSilver – Live Gold & Silver Price Charts (September 18, 2026)
2. GoldSilver – Ray Dalio’s Gold Strategy: Why He Recommends 5-15% in Gold (March 13, 2026)
3. Incrementum AG – In Gold We Trust 2026 (May 20, 2026)
4. GoldSilver – Silver Demand by Sector: Industry, Jewelry & Investment (April 1, 2026)
5. CFTC – Commitments of Traders (September 8, 2026)
6. FRED – 10-Year Real Yield, DFII10 (September 16, 2026)
7. FRED – 10-Year Breakeven Inflation Rate, T10YIE (September 17, 2026)
8. GoldSilver – 7 Timeless Warren Buffett Rules for Gold & Silver Investors (May 8, 2026)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Always consult a qualified financial advisor before making investment decisions.
You May Also Like:
- Who Owns US Debt? Central Banks Own Less Than You Think
- What Is Junk Silver? The Old Dimes and Quarters Worth Nearly 50x Their Face Value
- Why Is Silver Demand Tied to AI Data Centers?
- The Copper Mine That Isn’t Trying to Mine Silver Just Explained the Whole Deficit
- Inherited Gold IRA: Beneficiary Rules & the Step-Up Basis Gap
- The Cantillon Effect: Why Money Printing Makes Some People Rich First
- Silver Price Outlook September 2026: The Hike Is Priced In. The Positioning Isn’t.