Silver Rises Over 120% YTD


Published: 10-02-2026, 12:08 pm
Gold is barely moved today. It’s trading in the mid-$4,100s, roughly 5% below the $4,370 high it touched in late September, while silver sits just above $60, down more than 10% from its own September high near $67.50. It’s a quiet session by recent standards. The more interesting move isn’t in the price. It’s in a question the Official Monetary and Financial Institutions Forum (OMFIF) put directly to the market today: when should a central bank sell its gold?
Key Takeaways:
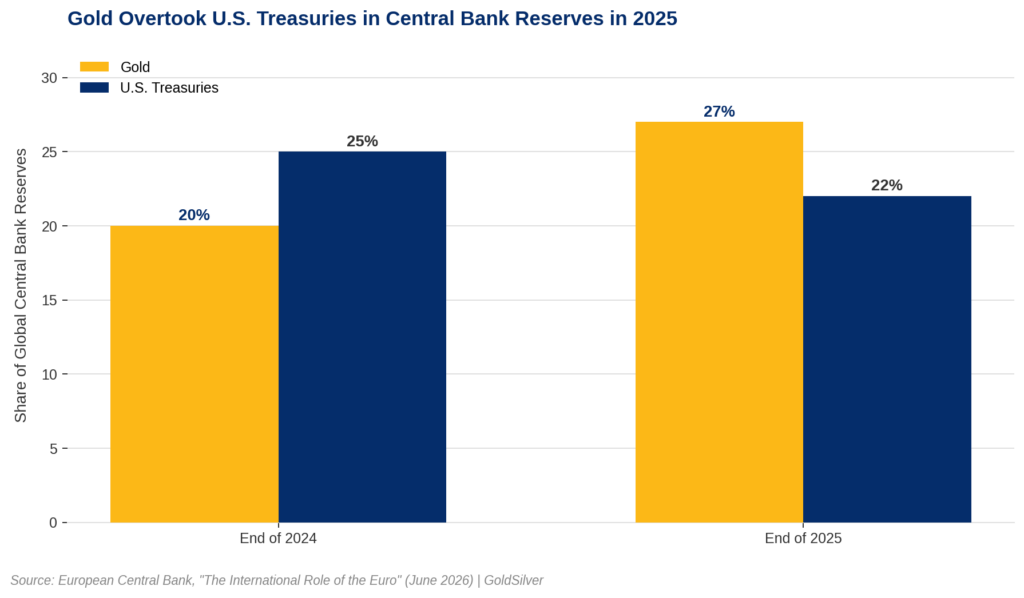
- OMFIF asked today whether central banks should sell gold; the European Central Bank’s own June 2026 data shows the opposite trend, gold’s reserve share rose to 27% in 2025 and overtook U.S. Treasuries at 22%.
- Turkey’s 130-tonne sale in early 2026 was a currency-defense move under acute stress, not evidence of a broader shift; OMFIF’s 2026 survey found 82% of central banks still hold gold (up from 71%) and a net 30% plan to add more.
- Western central banks hold roughly 60-70% of reserves in gold versus 5-10% for emerging-market banks, a gap that, if it closes, implies years of additional global mine production in demand.
Why Would a Central Bank Sell Gold?
It’s a fair question to ask in 2026. Turkey sold or loaned 130 tonnes of gold in early 2026. The Iran war had strained its currency and its finances. That followed 220 tonnes accumulated since 2022, according to the European Central Bank. The ECB called it one of the largest reserve drawdowns in recent years. Russia sold gold early in the year too, and Poland has said it would sell part of its reserves to help fund defense spending, part of the same post-2022 reserve-freeze caution this desk has covered before. For anyone watching central banks as a leading indicator for gold, a seller shows up and the question writes itself: is the buying over?
The Edge Every Investor Needs Smarter precious metals investing starts here. The Nuggets Newsletter brings you essential market insights, Fed updates, global trends, educational videos, and much more.
Has Gold Really Overtaken the Dollar System?
The data says no. And it says why. The same ECB report that documented Turkey’s sale also found something larger. Gold’s share of total global central bank reserves climbed to 27% by the end of 2025, up from 20% the year before. That overtook U.S. Treasuries, whose share fell to 22% from 25%. Central banks now hold more than 36,000 tonnes of gold combined, a level the ECB compared to the peak of the Bretton Woods era. The ECB was careful to note dollar-denominated assets overall still make up 42% of global reserves. The dollar remains dominant. This is a reshuffling of the reserve mix, not the end of the dollar system. But within that mix, gold just passed the asset it was supposedly competing with for decades.
What Do the Actual Survey Numbers Say?
OMFIF’s own research explains the mechanism better than any single sale does. Its 2026 Global Public Investor survey covered 90 central banks, pension funds and sovereign funds managing more than $10 trillion combined. It found 82% of central banks now hold physical gold, up from 71% a year earlier. A net 30% plan to add to their gold allocation over the next one to two years. Sixty-one percent expect gold to settle between $5,000 and $6,000 an ounce by June 2027. Separately, the World Gold Council’s 2026 Central Bank Gold Reserves Survey drew a record 76 respondents. It found only 46% of central banks now cite historical legacy as a reason to hold gold, down from 62% in 2025. That’s not central banks losing interest in the old reasons to own gold. It’s central banks increasingly managing it as a live strategic allocation rather than a dusty inheritance. That’s a reason to hold more deliberately, not less.
So, When Should a Central Bank Sell Its Gold?
That’s the actual answer to OMFIF’s question. A central bank sells gold when it needs cash fast and gold is the asset it can mobilize. Turkey did exactly that under currency pressure. That isn’t a verdict on gold as an asset class. It’s a liquidity decision, made by a handful of reserve managers under acute, country-specific stress. The large majority of the cohort is doing the opposite.
What Should Individual Gold Owners Take From This?
There’s a practical read-through here, and it isn’t about timing a sale. Western central banks, including the U.S., Germany, France, Italy and Switzerland, still hold an estimated 60 to 70% of their foreign exchange reserves in gold. Emerging-market central banks average closer to 5 to 10%. If that gap closes even halfway, the additional demand runs into the thousands of tonnes. That’s several years of global mine production. Reserve managers who already hold gold are not the ones selling it. The more useful question for most readers isn’t whether central banks will keep buying. It’s whether their own portfolio looks anything like the allocation the institutions holding the most gold have settled on. Our allocation calculator walks through that comparison directly. Watch for the World Gold Council’s Q3 2026 central bank buying report, typically released in late October, and any follow-up from OMFIF naming specific reserve managers’ near-term plans.
Stay On Top of Gold & Silver Prices
Get important market alerts sent straight to your inbox.
SOURCES
1. OMFIF – When Should a Central Bank Sell Its Gold? – October 2, 2026
2. OMFIF – Global Public Investor 2026 – June 30, 2026
3. European Central Bank – The International Role of the Euro – June 2, 2026
4. World Gold Council – Central Banks Set to Step Up Gold Buying Over the Next Year – June 16, 2026
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Always consult a qualified financial advisor before making investment decisions.
You May Also Like:
- September Payrolls Just Missed by 70,000. Gold and Silver Didn’t Wait to React.
- The ISM Number Barely Moved. The One Underneath It Just Jumped.
- Morgan Stanley Just Named Gold’s Floor. Here’s the Number.
- Gold Steadies Near $4,180. A GDP Upgrade Just Undercut the Inflation Miss.
- BlackRock Called It a Supercycle Today. The Mines and Vaults Already Agree.
- Gold Jumps as Core PCE Cools More Than Expected, Overshadowing the ADP Jobs Beat
- Job Openings Missed Today. That’s Exactly Why Gold Caught a Bid.
- Gold Fell Again. Five Wall Street Desks Can’t Agree on Why.
- Gold Just Hit a Two-Month Low. Yields, Not Iran, Are Why.