Silver Rises Over 120% YTD


Published: 08-27-2026, 03:50 pm | Updated: 08-27-2026, 03:56 pm
Silver is trading near $69.20 an ounce today, close to its highest levels since May. However, the more interesting number this week isn’t the spot price. Instead, it’s what’s happening inside COMEX’s own delivery system, three business days before September’s silver contract reaches First Notice Day.
The Edge Every Investor Needs Smarter precious metals investing starts here. The Nuggets Newsletter brings you essential market insights, Fed updates, global trends, educational videos, and much more.
What Is First Notice Day, and Why Does It Matter for Silver?
First Notice Day is when futures holders must decide: close the position, roll it forward, or stand for physical delivery. Each COMEX silver contract represents a claim on 5,000 troy ounces. Most holders never intend to take delivery. Instead, they’re trading price exposure, not buying bullion. Some do stand for delivery, however, and that’s where a contract stops being paper and becomes a request for real silver.
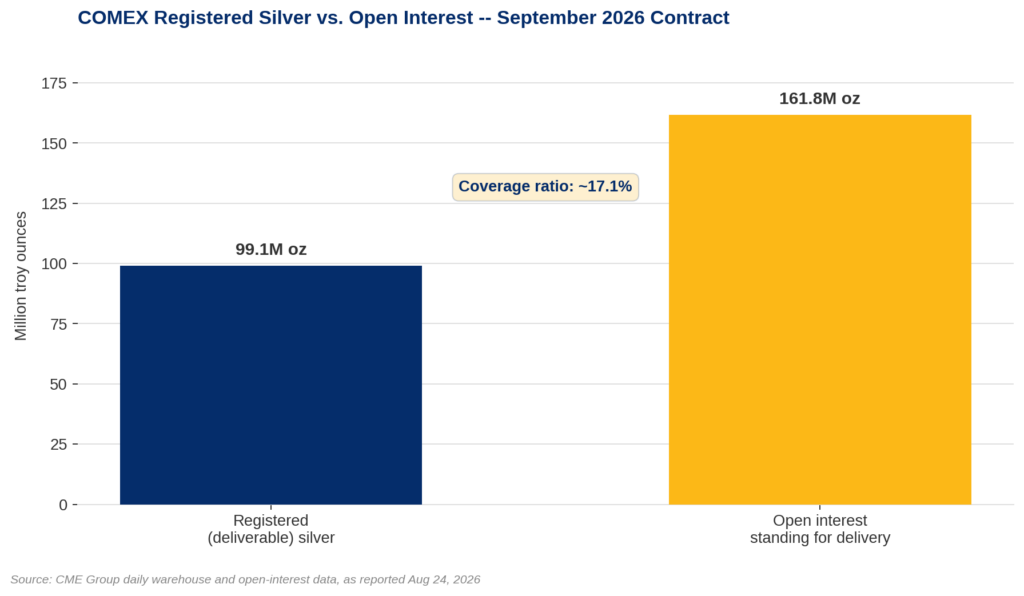
As of CME Group’s most recent reporting window, the September 2026 contract still had 32,363 contracts open. In other words, that’s 161.8 million ounces standing against a market with roughly 99.1 million ounces of registered, deliverable silver. Consequently, that gap is the story.
How Much Deliverable Silver Does COMEX Actually Have?
COMEX-approved warehouses hold silver in two buckets. Registered silver carries an active warehouse warrant, so it’s immediately available for delivery. Eligible silver sits in the same vaults and meets the same standard, but its owner hasn’t chosen to warrant it yet.
As of the most recent CME Group warehouse report, registered stocks stood at roughly 99.1 million ounces. Meanwhile, another 238.7 million ounces sat classified as eligible but not warranted. Divide open interest by registered stock, and a simple ratio emerges. Analysts call it the coverage ratio, and it currently sits near 17.1%, tight by historical standards though not unprecedented.
For comparison, the same measurement at April’s First Notice Day sat closer to 13-14%. In other words, the ratio has loosened since spring, even as the contract’s open interest fell sharply, from 81,726 contracts on July 24 to today’s 32,363.
That decline is normal, not alarming. Specifically, most speculators roll out of a delivery month before it arrives because they don’t want the metal. As a result, a shrinking open-interest count tells you little on its own. Instead, the ratio those remaining contracts represent against the vault is what’s structurally interesting.
Why Does the Coverage Ratio Matter If Most Contracts Never Stand for Delivery?
Because the ratio isn’t a prediction. It’s a fact about the system’s plumbing, and it recurs every delivery month regardless of Fed policy or where gold trades. In short, a futures contract is a legal claim on silver, not silver itself. Registered inventory, by contrast, is the pile the exchange can hand over if enough holders ask at once. The coverage ratio simply measures how much of the paper market that pile could satisfy today.
In practice, the exchange has never defaulted on a silver delivery. Part of the reason is mechanical: a depository receipt for specific vaulted bars can change hands two or three times within one delivery month without reducing registered inventory at all. A long holder can stand for delivery, take the receipt, then redeliver that same metal the next day, and the registered count never moves.
That mechanism alone means gross delivery activity routinely overstates real drawdown. CME Group’s own 2026 precious metals outlook describes the silver market as increasingly focused on physical balances, with industrial consumption outpacing mine supply for a fifth consecutive year. Nevertheless, a market where paper claims outnumber deliverable metal roughly 5.8 to 1 is worth understanding on its own terms. Here, the gap between owning silver and owning a claim on it isn’t academic.
What Does This Mean for Someone Deciding Between Paper and Physical Silver?
This is where the mechanism meets a choice individual savers actually face. An ETF share or a futures contract gives you price exposure to silver. It doesn’t give you silver sitting in your name, ready for delivery on demand. That’s true unless you’re one of the relatively few participants who stand for delivery each month and successfully take metal.
The coverage ratio, in short, is a live demonstration of how much of the paper market could convert to metal at once. Beyond the redelivery mechanism above, the exchange’s rulebook includes emergency provisions for extreme scenarios, though none have ever been invoked for a silver delivery month. What the ratio shows, month after month, is a structural gap between the paper market’s size and the vault behind it. For a saver weighing physical ownership against paper exposure, that gap is the entire argument.
What Should Investors Watch Next?
September’s First Notice Day lands within days. Watch whether the remaining contracts keep rolling off at their recent pace. Watch too whether registered inventory moves materially, and whether the ratio holds near 17.1% or tightens further. The same measurement repeats at December’s First Notice Day, and each reading adds another data point to a pattern that has held all year.
Separately, gold and silver both remain near multi-month highs heading into Friday’s Jackson Hole speech from Fed Chair Kevin Warsh. That catalyst is unrelated to the mechanics above, however, and it’s worth tracking on its own terms. Our prior coverage of April’s First Notice Day walked through the same mechanism at a tighter 13-14% ratio. For more on what registered versus eligible inventory means, see our breakdown of the coverage ratio itself.
Stay On Top of Gold & Silver Prices
Get important market alerts sent straight to your inbox.
SOURCES
1. CME Group — Precious Metals Outlook 2026: Market Dynamics Following a Record-Breaking Year
2. CME Group — Historical Registrar Reports, Warehouse & Depository Stocks (Silver Stocks), accessed August 27, 2026
3. CME Group — Daily Information Bulletin, Metals Futures Products (Section 62), July 24, 2026
4. COMEX September 2026 silver contract open interest and registered/eligible warehouse figures, as reported by independent market-data aggregators reading CME Group’s daily and weekly published data (Aug 24, 2026 reporting window)
5. Jeffrey Christian, Managing Director, CPM Group — on depository receipt redelivery mechanics within a single COMEX delivery month, as reported by Discovery Alert, June 12, 2026
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Always consult a qualified financial advisor before making investment decisions.
You May Also Like:
- Five Gold Signals Fired This Week. None of Them Are About Today’s Price.
- Gold Fell 9% the Last Time Warsh Spoke. He’s Back Tomorrow.
- Gold Ran Past Wall Street’s Own Price Targets. Four Banks Disagree on What Happens Next.
- Silver Beat Gold in August. Almost Nobody Said So.
- Americans Spent More in July. They Got Nothing Extra for It.
- The Fed Has Two Hike Numbers Right Now. Almost Everyone Quotes the Wrong One.
- Gold and Silver Pulled Back Today. The Treasury’s Plumbing Explains Why.