Silver Rises Over 120% YTD


Published: 10-05-2026, 04:27 pm
The Federal Reserve may not need another rate hike to tighten financial conditions. Long-term Treasury yields are already doing part of that work. For gold investors, the key question is now why those yields remain so high.
Key Takeaways:
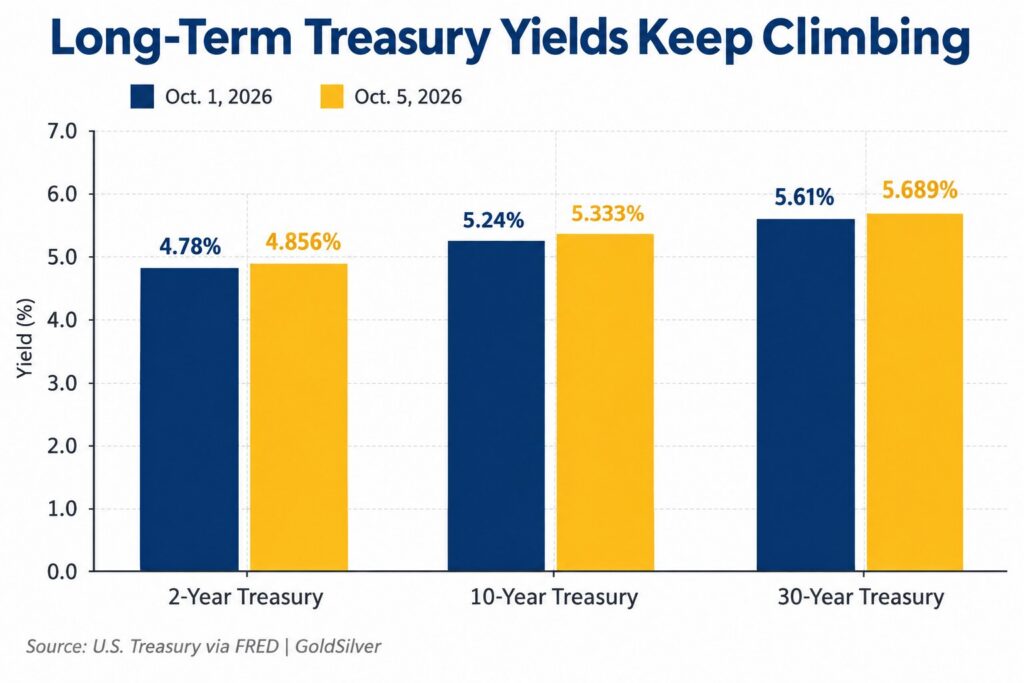
- The 10-year Treasury yield reached 5.333% on October 5, even as markets favored a Fed hold.
- Higher real yields can pressure gold by raising the opportunity cost of holding a non-yielding asset.
- However, persistent long-term yields can also signal inflation, fiscal, supply, or term-premium concerns that matter to gold’s longer-term role.
Why Are Treasury Yields Rising If the Fed May Hold?
Long-term yields reflect more than the Fed’s next decision. They also reflect growth, inflation, Treasury supply, fiscal risk, and term premium.
The Wall Street Journal reported that the 10-year Treasury yield reached 5.333% on October 5. The 30-year reached 5.689%, while the two-year rose to 4.856%. At the same time, markets were pricing in a Fed hold for October.
That combination matters. It suggests the bond market can keep financial conditions tight without another immediate Fed hike.
The Fed directly controls its short-term policy rate. It does not directly set the 10-year or 30-year Treasury yield. Therefore, higher long-term yields can lift borrowing costs across the economy on their own.
GoldSilver saw an earlier version of this pressure in September. A weak Treasury auction pushed yields to their highest levels in years. Today’s story is different. Long-term yields remain elevated even as expectations for an immediate Fed hike have eased.
The Edge Every Investor Needs Smarter precious metals investing starts here. The Nuggets Newsletter brings you essential market insights, Fed updates, global trends, educational videos, and much more.
Why Do Higher Treasury Yields Pressure Gold?
Higher yields can make bonds more attractive relative to gold. Gold pays no coupon or interest. As a result, rising bond returns can increase the opportunity cost of holding it.
A stronger dollar can add pressure. Because gold is priced in dollars, a stronger currency can make the metal more expensive for overseas buyers.
However, nominal yields are only part of the picture. Real yields matter more directly to gold because they adjust bond returns for inflation.
GoldSilver’s guide to real yields versus nominal rates explains this relationship. When real yields rise, the relative cost of holding non-yielding gold usually increases.
Federal Reserve H.15 data also confirm how elevated the curve became by October 1. The two-year stood at 4.78%, the 10-year at 5.24%, and the 30-year at 5.61%.
So, higher real yields remain a genuine near-term headwind for gold.
Why Is This Treasury Move Different From September?
September showed that the entire Treasury curve could reprice sharply. Reuters reported that the 10-year yield rose about 50 basis points during September. The two-year rose by roughly the same amount.
The latest move adds another layer.
October rate-hike expectations have fallen, yet long-term yields remain historically elevated. Barron’s reported on October 2 that the implied probability of an October hike had fallen to 13.8%.
Therefore, a Fed pause does not automatically mean easier financial conditions.
The long end of the Treasury market has its own vote.
Could High Treasury Yields Strengthen Gold’s Longer-Term Case?
Potentially, but not because high yields themselves are bullish for gold.
Higher real yields are normally a headwind. That relationship should not be ignored.
Instead, investors should examine what is driving those yields.
Persistent inflation could be one factor. Heavy Treasury issuance could be another. Fiscal uncertainty and a higher term premium may also contribute.
These forces can create two competing effects.
First, higher real returns make gold relatively less attractive in the short term. Second, concerns about inflation or fiscal sustainability can strengthen demand for monetary diversification over longer periods.
Both forces can exist at the same time.
What Should Gold Investors Watch Next?
First, watch the two-year and 10-year Treasury yields together.
If the two-year falls as Fed-hike expectations decline, but the 10-year stays above 5%, the message becomes clearer. Longer-term forces would be keeping borrowing costs elevated.
Second, watch real yields. Rising real yields would likely remain difficult for gold. Falling real yields would reduce that pressure, even if nominal Treasury yields stayed high.
Finally, watch demand for longer-dated Treasury debt. Weak auctions or persistent selling could show that investors want more compensation to hold long-term government bonds.
For gold investors, the next Fed meeting is only one part of the story. The bigger question is whether the Treasury market keeps tightening even when the Fed does not.
Stay On Top of Gold & Silver Prices
Get important market alerts sent straight to your inbox.
SOURCES
1. Federal Reserve Board – H.15 Selected Interest Rates – October 2, 2026
2. The Wall Street Journal – U.S. Treasury Yields Climb After Early Softness – October 5, 2026
3. CME Group – CME FedWatch Tool – October 5, 2026
4. Reuters – Bonds Set for Bruising September as Treasury Yields Surge – September 30, 2026
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Always consult a qualified financial advisor before making investment decisions.
You May Also Like:
- Who’s Actually Right About Gold Right Now? Five Signals, Five Answers
- Gold and Silver Are Rising Today. So Is the Dollar. That’s Rare.
- When Should a Central Bank Sell Its Gold? One Just Did. Most Won’t.
- September Payrolls Just Missed by 70,000. Gold and Silver Didn’t Wait to React.
- The ISM Number Barely Moved. The One Underneath It Just Jumped.
- Morgan Stanley Just Named Gold’s Floor. Here’s the Number.
- Gold Steadies Near $4,180. A GDP Upgrade Just Undercut the Inflation Miss.
- BlackRock Called It a Supercycle Today. The Mines and Vaults Already Agree.
- Gold Jumps as Core PCE Cools More Than Expected, Overshadowing the ADP Jobs Beat